

An EDI payment is a business-to-business payment where the payment instructions and remittance details are exchanged as standardized electronic data interchange (EDI) messages, most often the ANSI X12 820. EDI carries the information about the payment. The money itself moves over a payment rail such as ACH or wire.
B2B payments are moving fast. According to Nacha, the US ACH Network processed 35.2 billion payments worth $93 trillion in 2025, including about 8.1 billion business-to-business payments, up nearly 10% from 2024. Every one of those B2B payments raises the same question for the supplier: which invoices is this for? EDI answers it.
What Are EDI Payments?
Electronic data interchange (EDI) is the computer-to-computer exchange of business documents in a standard format, such as ANSI X12 in North America and EDIFACT internationally. EDI payments use those standards for the financial side of a trade relationship:
Invoices (EDI 810) sent from supplier to buyer
Payment orders and remittance advice (EDI 820) sent from buyer to its bank or to the supplier
Lockbox and bank reporting documents (for example, EDI 823) sent from banks to the payee
Because every field sits in a defined position, the receiving system can read the data without anyone retyping it. An EDI 820 can tell a supplier's ERP that a $48,210 payment covers invoices 10431, 10436 and 10440, minus a $150 deduction, and the ERP can apply the cash automatically. Learn more about EDI standards and EDI documents.
How Do EDI Payments Work?
EDI payments work in five steps: the supplier sends an EDI 810 invoice, the buyer sends an EDI 820 payment order to its bank, the bank moves the funds by ACH or wire with the remittance attached, the supplier's bank passes along the funds and remittance, and the supplier's ERP applies the cash automatically.
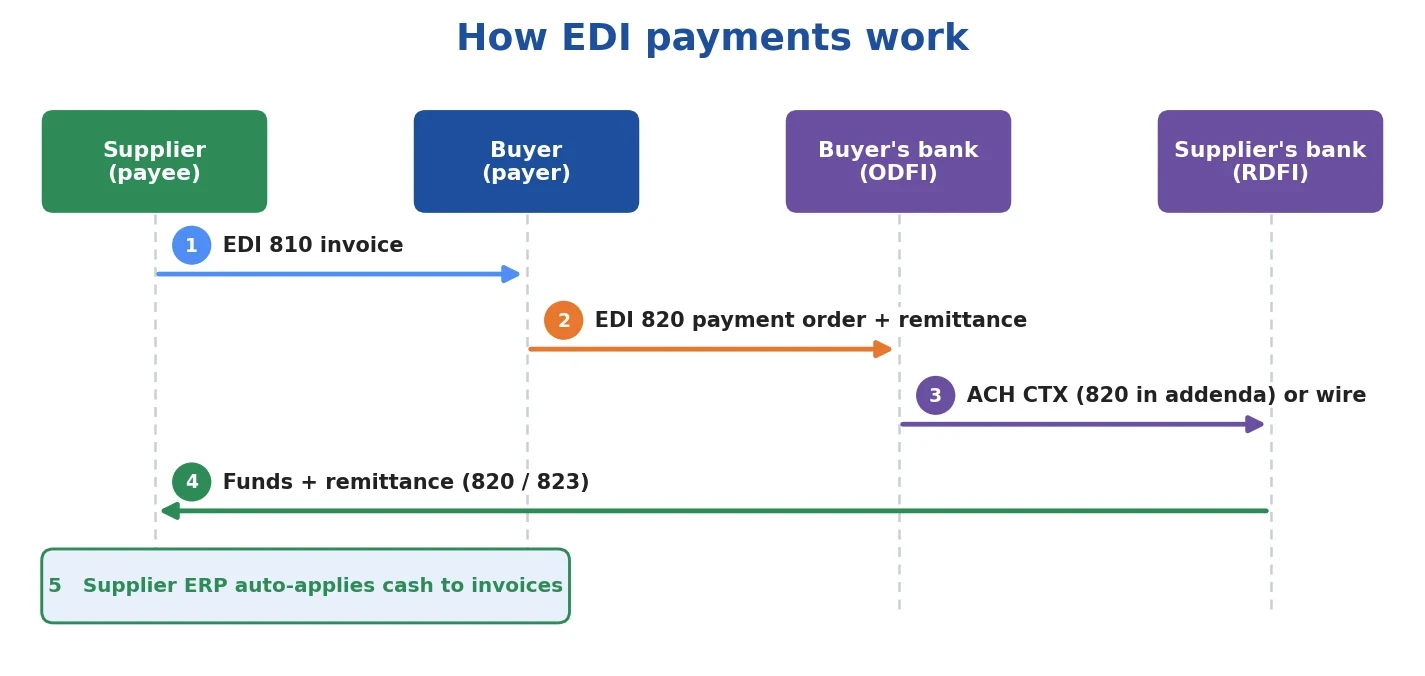
Invoice. The supplier sends an EDI 810 invoice to the buyer, usually after an EDI 850 purchase order and a shipment.
Payment order. The buyer's accounts payable system approves the invoice and creates an EDI 820 that lists the invoices being paid, the amounts and any adjustments. The buyer sends it to its bank, known as the originating depository financial institution (ODFI).
Funds transfer. The bank originates the payment. For ACH, it uses the CTX format, which carries the 820 remittance in addenda records alongside the money. For large or urgent payments, it may send a wire instead.
Delivery. The supplier's bank (RDFI) credits the account and delivers the remittance data, either as an 820 or in a lockbox format such as the EDI 823.
Cash application. The supplier's ERP reads the remittance and matches the payment to open invoices, with no manual lookup.
Some buyers send the 820 directly to the supplier (through a VAN, AS2 or SFTP) while the money travels separately by ACH or wire. The result is the same: structured remittance that the supplier's system can post automatically.
EDI vs. ACH vs. EFT: What's the Difference?
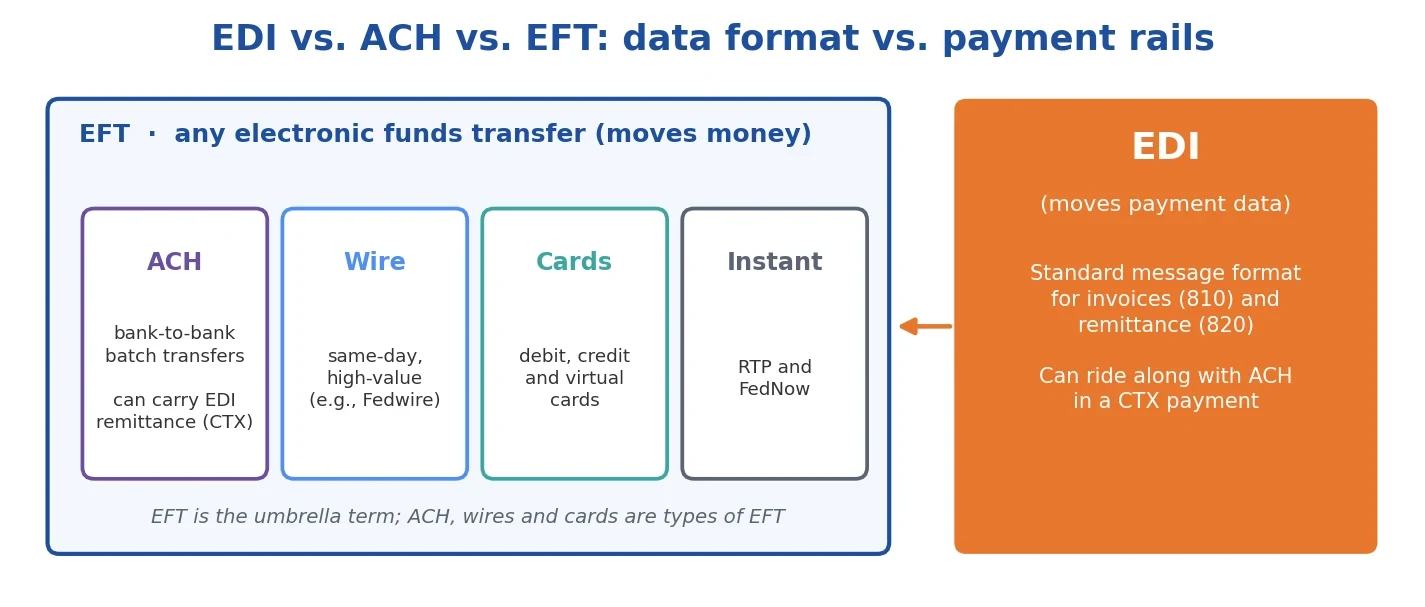
EDI is a standard format for exchanging payment data, while ACH and EFT move money. EFT (electronic funds transfer) is the umbrella term for any electronic money movement. ACH is one type of EFT: a US bank-to-bank network governed by Nacha rules. EDI data can travel with an ACH payment, most often in the CTX format.
EDI | ACH | EFT | |
What it is | Data exchange standard | US bank payment network | Umbrella term for electronic payments |
Moves | Invoices, remittance, orders | Money (batch transfers) | Money (any electronic method) |
Examples | X12 810, 820, 823; EDIFACT REMADV | Payroll direct deposit, B2B vendor payments (CCD+, CTX) | ACH, wires, debit and credit cards, instant payments |
Governed by | X12 / UN/EDIFACT standards | Nacha Operating Rules | Varies by rail |
Speed | Minutes (data delivery) | Same day or 1–2 business days | Seconds to days, depending on rail |
Role in EDI payments | Carries remittance and payment instructions | Settles the funds and can carry the 820 in CTX addenda | Category that includes the settlement rail |
What about wire transfers?
Wires are also a type of EFT. They settle individually and usually within hours, which makes them useful for large or time-critical payments, but they typically carry fees and far less room for remittance data than a CTX. For ACH, Nacha has approved raising the Same Day ACH limit from $1 million to $10 million per payment, effective September 17, 2027, which will let more high-value B2B payments move same-day over ACH.
EDI Transaction Sets Used for Payments
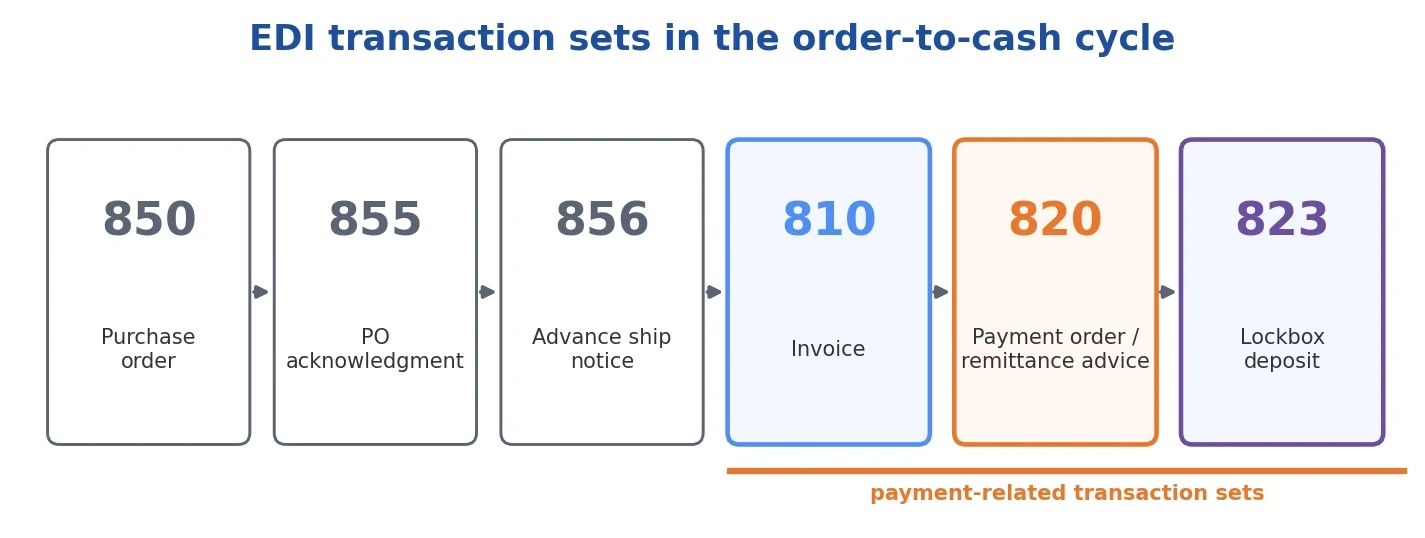
EDI payments are the final steps of the order-to-cash cycle, which runs from purchase order to cash received:
Transaction set | Name | Used for |
EDI 810 | Invoice | Supplier bills the buyer for goods or services |
EDI 820 | Payment Order/Remittance Advice | Buyer instructs its bank to pay, or tells the supplier what is being paid |
EDI 823 | Lockbox | Bank reports lockbox deposits and remittance to the payee |
EDI 835 | Health Care Claim Payment/Advice | Health plans explain claim payments to providers (see EDI 835 and EDI 834, 835 and 837) |
EDI 997 / 999 | Functional / Implementation Acknowledgment | Confirms that an EDI file was received and passed validation |
EDI 820 vs. EDI 810
The EDI 810 says what is owed; the EDI 820 says what is being paid. The supplier sends the 810 to request payment. The buyer sends the 820 to pay one or more invoices, and it can note short payments, discounts and deductions so the supplier knows why an amount differs.
CTX vs. CCD+: How remittance travels with ACH
Nacha defines two main ACH formats for business payments. CCD+ carries one 80-character addenda record, which is enough for a single invoice number. CTX carries up to 9,999 addenda records, around 800,000 characters in total, which is enough for a full EDI 820 covering hundreds of invoices. If your customers pay many invoices at once, ask them to use CTX.
How EDI Payment Data Is Transmitted
Trading partners exchange EDI payment documents using one or more of these communication methods:
Through the bank (financial EDI): the 820 travels with the payment in an ACH CTX, or is delivered by the bank separately.
AS2 or SFTP (direct): a secure point-to-point connection between partners. This is common for high-volume relationships.
VAN: a value-added network acts as a secure mailbox between partners and handles routing and tracking.
Web EDI: a browser portal for low-volume partners, which converts form entries into EDI documents.
Manual vs. EDI Payment Process
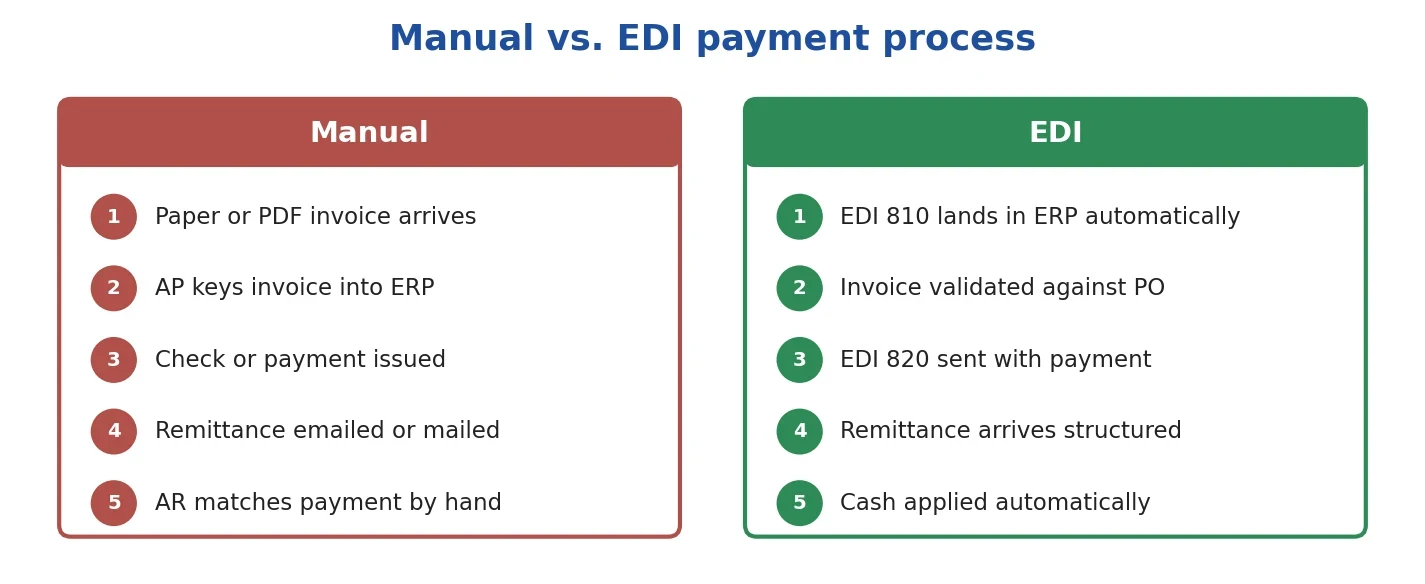
In a manual process, someone keys each invoice into the ERP, issues a check or payment, emails a remittance PDF, and then AR matches the payment by hand, often chasing the customer to find out which invoices were paid. With EDI, the invoice arrives in the ERP, the remittance arrives structured, and the payment posts itself. The gains are fastest in accounts receivable, where unapplied cash and short-pay research eat the most time.
Benefits of EDI Payments
Automatic cash application. Structured remittance lets the ERP match payments to invoices without manual work.
Fewer errors and disputes. There's no rekeying, and deductions and adjustments are coded rather than buried in emails.
Faster order-to-cash. Invoices arrive instantly, and payments post the day they land.
Better cash-flow visibility. AR and treasury see exactly what has been paid and what is still open.
Lower processing costs. Less paper, fewer checks and less time spent chasing remittance.
Security and auditability. Encrypted transmission, acknowledgments (997/999) and a clear audit trail for every document.
Stronger trading relationships. Many large buyers require EDI, and meeting that requirement keeps suppliers compliant and paid on time.
Challenges of EDI Payments
Challenge | How to address it |
Partner-specific formats | Each partner has its own 820 implementation guide. Use reusable EDI mapping templates for each partner. |
Remittance and money arriving separately | Match payments to 820s automatically by trace number, amount and date. |
Bank and partner onboarding | Plan for testing cycles with banks and major customers, and start with your highest-volume partners. |
ERP integration | Choose a tool that translates EDI directly into your ERP's formats and posts cash without file handoffs. |
Errors and exceptions | Monitor acknowledgments, set alerts for rejected files, and route short pays to a review queue. |
How to Get Started With EDI Payments
Identify your partners and volume. List which customers and suppliers can send or receive 810s and 820s, and which ones require them.
Talk to your bank. Confirm it supports CTX and can deliver 820 or 823 remittance files to you.
Collect implementation guides. Get each partner's 810 and 820 specifications, including versions, required segments and qualifiers.
Choose connectivity. Pick AS2, SFTP, a VAN or web EDI for each partner.
Map to your ERP. Map EDI fields to your AR and AP data and define matching rules for cash application.
Test, then go live gradually. Start with one or two partners, validate acknowledgments and posting, then scale.
Compare options in our guide to EDI tools, or read more about EDI transactions.
Keep Learning
EDI basics: What is EDI?, EDI standards and EDI documents
Transaction sets: EDI 850, EDI 810 and EDI 835
Implementation: EDI mapping, EDI communication methods and EDI tools
Automate EDI Payments With Astera EDIConnect
Astera EDIConnect lets you exchange invoices and payment documents with trading partners over AS2, FTP, SFTP and APIs. It translates EDI into your ERP's formats, sends acknowledgments automatically, and tracks every file from a central dashboard with alerts for errors, so remittance goes from partner to posted cash without manual steps.
Start using EDI payments and boost your financial processes
View Demo